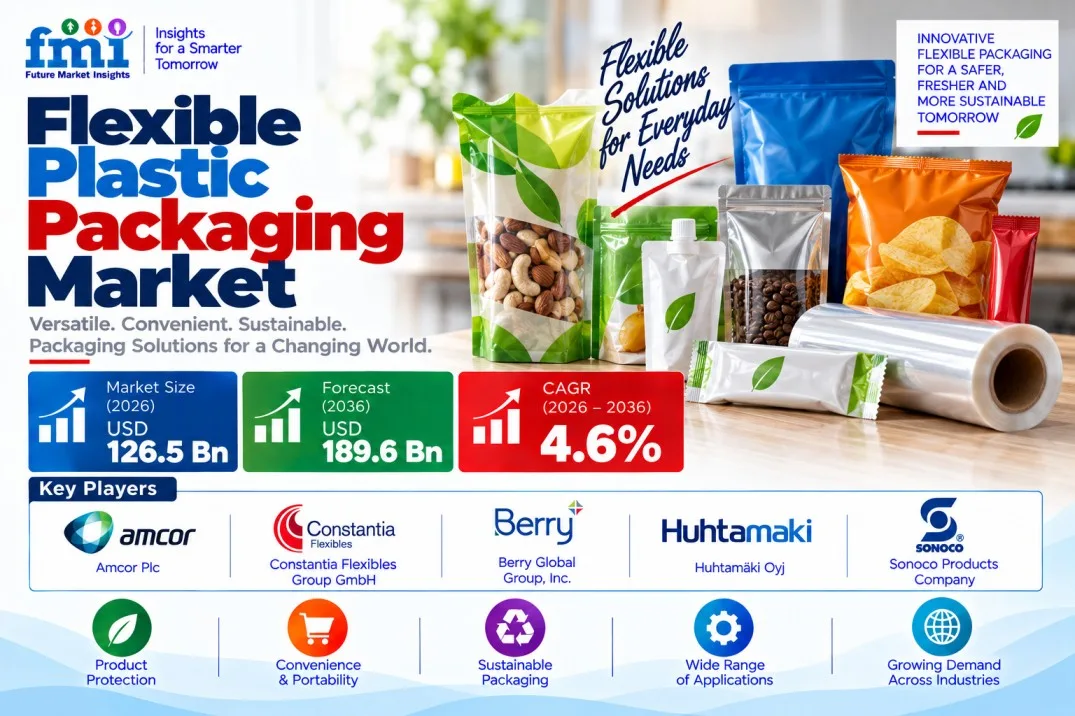
The global flexible plastic packaging market is projected to grow from USD 126.5 billion in 2026 to USD 189.6 billion by 2036, expanding at a 4.6% CAGR, as food, pharmaceutical, personal care, and industrial packaging demand continues to favor lightweight films, pouches, wraps, and other flexible formats.
The market's sustainability challenge has become more immediate in Europe. The European Union's Packaging and Packaging Waste Regulation (PPWR) began applying on August 12, 2026, while requirements that all packaging be recyclable apply from 2030.
That timing is pushing flexible packaging suppliers to address a difficult combination: maintaining shelf life, seal performance, and pack strength while simplifying structures and improving recyclability.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
https://www.futuremarketinsights.com/reports/sample/rep-g…
Why is flexible packaging being redesigned rather than simply replaced?
Flexible plastic packaging continues to benefit from its ability to deliver product protection with relatively low material weight. Films and wraps are expected to account for 36.8% of product demand in 2026, while oil-based polymers are projected to hold 58.0% of material demand.
Food remains a major source of volume because meat, dairy, snacks, bakery products, and fresh produce require barrier and sealing performance that can be difficult to replicate with alternative materials.
High-barrier structures are particularly important where oxygen and moisture control determine shelf life. Modified-atmosphere packaging is projected to represent 45.8% of packaging-type demand in 2026, reflecting continued use in fresh food applications.
The sustainability transition therefore is not simply a shift from plastic to another material. In many applications, converters are redesigning the plastic structure itself—reducing material weight, moving toward mono-material PE or PP formats, and testing recycled content where pe
Sign in to join the conversation.