Jere

Jere

Loading…

Jere
Welcome
Sign in to manage your account.
HomeEarnAdvertiseWatch AdsDaily BonusOffer WallPlay & EarnPollsRewardsWalletBlog
FAQWeb Development
Log InSign Up
🎉 New rewards added! Check the Rewards Store →

Vishal Panchmukh

@vishal_panchmukh
Joined September 2026
The global flexible plastic packaging market is projected to grow from USD 126.5 billion in 2026 to USD 189.6 billion by 2036, expanding at a 4.6% CAGR, as food, pharmaceutical, personal care, and industrial packaging demand continues to favor lightweight films, pouches, wraps, and other flexible formats.
The market's sustainability challenge has become more immediate in Europe. The European Union's Packaging and Packaging Waste Regulation (PPWR) began applying on August 12, 2026, while requirements that all packaging be recyclable apply from 2030.
That timing is pushing flexible packaging suppliers to address a difficult combination: maintaining shelf life, seal performance, and pack strength while simplifying structures and improving recyclability.
Get detailed market forecasts, competitive benchmarking, and pricing trends:
https://www.futuremarketinsights.com/reports/sample/rep-g…
Why is flexible packaging being redesigned rather than simply replaced?
Flexible plastic packaging continues to benefit from its ability to deliver product protection with relatively low material weight. Films and wraps are expected to account for 36.8% of product demand in 2026, while oil-based polymers are projected to hold 58.0% of material demand.
Food remains a major source of volume because meat, dairy, snacks, bakery products, and fresh produce require barrier and sealing performance that can be difficult to replicate with alternative materials.
High-barrier structures are particularly important where oxygen and moisture control determine shelf life. Modified-atmosphere packaging is projected to represent 45.8% of packaging-type demand in 2026, reflecting continued use in fresh food applications.
The sustainability transition therefore is not simply a shift from plastic to another material. In many applications, converters are redesigning the plastic structure itself—reducing material weight, moving toward mono-material PE or PP formats, and testing recycled content where pe
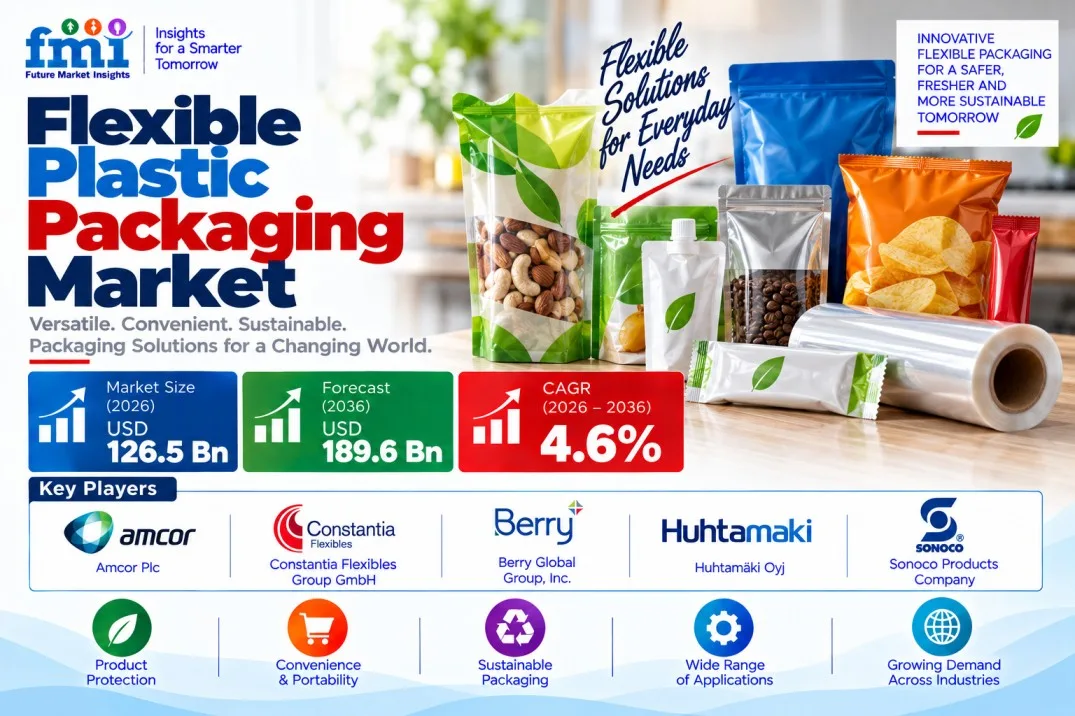
Photo 1
01 shares 25
Medical Specialty Bag Market Forecast to Grow at 8.9% CAGR, Reaching USD 9.6 Bn by 2036

The global medical specialty bag market is projected to grow from USD 4.1 billion in 2026 to USD 9.6 billion by 2036, expanding at a 8.9% CAGR, as ostomy care, hospital fluid management, urinary drainage, and home-based treatment increase demand for specialized collection and delivery bags.

The market was valued at USD 3.8 billion in 2025. Ostomy bags are expected to hold the largest product share at 34.0% in 2026, while PVC is projected to account for 42.0% of material demand. Disposable bags are expected to represent 71.0% of the market, reflecting the importance of infection-control requirements in clinical settings.

👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends:https://www.futuremarketinsights.com/reports/sample/rep-g…

Why are medical specialty bags becoming a care-continuity product?

Medical specialty bags increasingly span the entire care pathway rather than remaining limited to hospital procedures. Ostomy and urinary drainage products continue to generate recurring demand after discharge, while IV fluid, blood, drainage, and feeding bags support hospital-based treatment.

Ostomy care is particularly important because pouch replacement creates recurring purchasing requirements. Product design is also becoming more relevant to repeat selection. Convatec's February 2024 launch of Esteem Body with Leak Defense, for example, focused on pouch shape and wear performance, illustrating how manufacturers are competing on usability alongside basic fluid containment.

Homecare is adding another layer to demand. As more treatment and recovery takes place outside hospitals, patients and caregivers require products that are easier to handle, discreet, and reliable during routine use. This is shifting competition toward leakage control, skin compatibility, handling convenience, and dependable distribution.
Photo 1
01 shares 4
Wood Pallets Market to Advance at 5.4% CAGR, Reaching USD 4.69 Bn by 2035

The global wood pallets market is projected to grow from USD 2.77 billion in 2025 to USD 4.69 billion by 2035, advancing at a 5.4% CAGR, as international trade, e-commerce, food and beverage distribution, and pharmaceutical logistics sustain demand for durable and compliance-ready transport packaging.
Wood pallets remain closely linked to cross-border shipment requirements because international movements of wooden packaging generally require compliance with ISPM-15 phytosanitary treatment requirements. At the same time, pallet users are placing greater emphasis on reuse, refurbishment, traceability, and responsible timber sourcing as logistics networks seek to manage material costs and sustainability targets.
👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…
Why are compliance and reuse becoming central to pallet procurement?
International shipping continues to make treated wooden pallets an important component of global logistics. Exporters need pallet systems that can satisfy applicable phytosanitary requirements while remaining durable enough for repeated handling, storage, and transportation.
This is creating a market where pallet value increasingly extends beyond the initial manufacturing cost. Certified timber sourcing, heat-treatment capabilities, refurbishment networks, and pallet pooling can influence total lifecycle economics for large logistics operations.
The shift toward reuse is particularly relevant as timber prices and availability fluctuate. Instead of treating pallets as disposable transport components, logistics operators can use recovery and refurbishment networks to extend pallet life and reduce the need for replacement units.
The competitive landscape includes Interpak Industries Pvt. Ltd., Tri-Wall Holdings Limited, PalletOne, Falkenhahn AG, Larson Packaging Company, INKA Pale
Photo 1
01 shares 23
Barrier Film Market to Cross USD 68 Bn by 2036, USA - CAGR 5.1%, UK - CAGR 4.8%

The global barrier film market is projected to reach USD 68.48 billion by 2036, expanding at a 5.5% CAGR from 2026 to 2036, as food, pharmaceutical, and consumer-goods packaging applications increase demand for films that provide moisture, oxygen, aroma, and contamination protection.
The market is shifting toward barrier structures that combine performance with recyclability. Polyethylene (PE) is expected to account for 34.8% of the material type segment in 2026, while high-barrier films represent 36.2% of the product type segment. India and China are forecast to grow faster than the global market, at 5.9% and 5.7%, respectively.
👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…
Why are barrier film specifications changing?
Food manufacturers continue to rely on barrier films to extend shelf life and protect products from moisture ingress, oxygen transmission, and aroma loss. Pharmaceutical and medical packaging creates an additional layer of demand because film structures must meet tighter performance and material-compatibility specifications.
At the same time, sustainability requirements are changing how those performance characteristics are delivered. Traditional multilayer structures can combine polymers and metallized layers that complicate recycling, encouraging film producers to develop mono-material and recyclable alternatives.
This creates a technical challenge for the industry: recyclability cannot come at the expense of the barrier performance required by sensitive products. Suppliers therefore increasingly compete on their ability to engineer material structures that balance shelf-life protection, processability, recyclability, and cost.
The competitive landscape includes Berry Global Inc., Amcor Plc., Sealed Air, Toppan Printing Co., Ltd., Cosmo Films Ltd., Uflex Ltd., Jindal Poly
Photo 1
01 shares 2
Portion Sauce Cups with Lids Market to Cross USD 501 Mn by 2036, USA - CAGR 5.7%, UK - CAGR 5.4%

The regulatory shift comes as the global Portion Sauce Cups with Lids Market is projected to grow from USD 311.1 million in 2026 to USD 501.9 million by 2036, representing a 4.9% CAGR.
The market is not moving uniformly toward one replacement material. FMI expects PP portion cups to hold 36.0% of product-type demand in 2026, while paperboard leads the material category at 28.0%. Standard meal formats account for 43.0% of format-size demand, and QSR chains represent 28.0% of end-use demand.
👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…
Why Is the Cup-and-Lid System Becoming More Important Than the Cup Alone?
A condiment cup is inexpensive, but its failure occurs at the point where foodservice operators have the least tolerance for disruption.
A lid that leaks during delivery can create product loss, customer complaints and packaging waste. A cup that denests poorly can slow service. A lower-plastic material that weakens after contact with oily or acidic sauces can create a different form of operational failure.
That is why material substitution is increasingly being evaluated as a cup-and-lid system, rather than as a simple resin replacement.
The market includes Genpak, Dart Container, Sabert, Novolex, Huhtamaki, Duni, Berry Global, Pactiv Evergreen, Graphic Packaging and Detmold Group, with suppliers approaching the opportunity through conventional plastic formats, paperboard, molded fiber and lower-plastic structures.
The distinction is important because a successful alternative must maintain sauce barrier performance, dimensional stability, denesting and closure engagement while also meeting local recovery or regulatory requirements.
Photo 1
01 shares 1
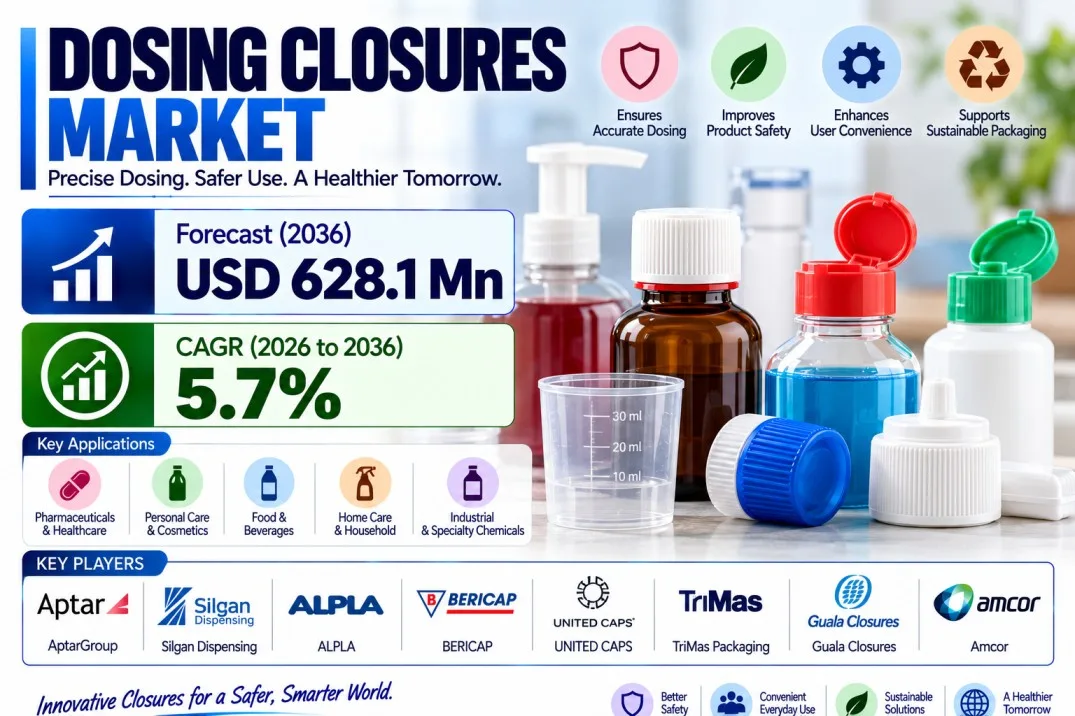
Dosing Closures Market Size to Reach USD 628.1 Mn by 2036, UAE - 7.1%, USA - 6.2%

The global Dosing Closures Market is projected to grow from USD 360.8 million in 2026 to USD 628.1 million by 2036, advancing at a 5.7% CAGR, as packaging programs increasingly evaluate dosing accuracy, child resistance, sealing performance and material compatibility as interconnected closure requirements.
In April 2026, the U.S. Consumer Product Safety Commission recalled approximately 356,140 packages of iron supplements because the packaging did not meet applicable child-resistant requirements. The action highlights how closure performance can become a commercial issue beyond dispensing convenience, particularly where regulated products require documented package-level safety.
The implications extend across food, beverage, personal care, home care and pharmaceutical applications. As packaging owners pursue simpler material structures, they must preserve torque, sealing, dispensing behavior and safety performance while meeting changing recyclability expectations.
👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…
Why are dosing closures becoming a package-level decision?
Dosing closures create value by controlling product flow while maintaining the usability and integrity of the package after repeated dispensing. The strongest applications are those where inaccurate flow, leakage, contamination or difficult reclosure creates measurable product or compliance costs.
FMI estimates that screw closures will account for 37.0% of market demand in 2026, making them the leading product type. Their established thread geometry allows manufacturers to incorporate dispensing, tamper-evident and safety features while retaining familiar bottle interfaces and capping-line configurations.
The competitive landscape spans engineered dispensing specialists and large closure manufacturers. AptarGroup, Silgan Di
Photo 1
01 shares 0
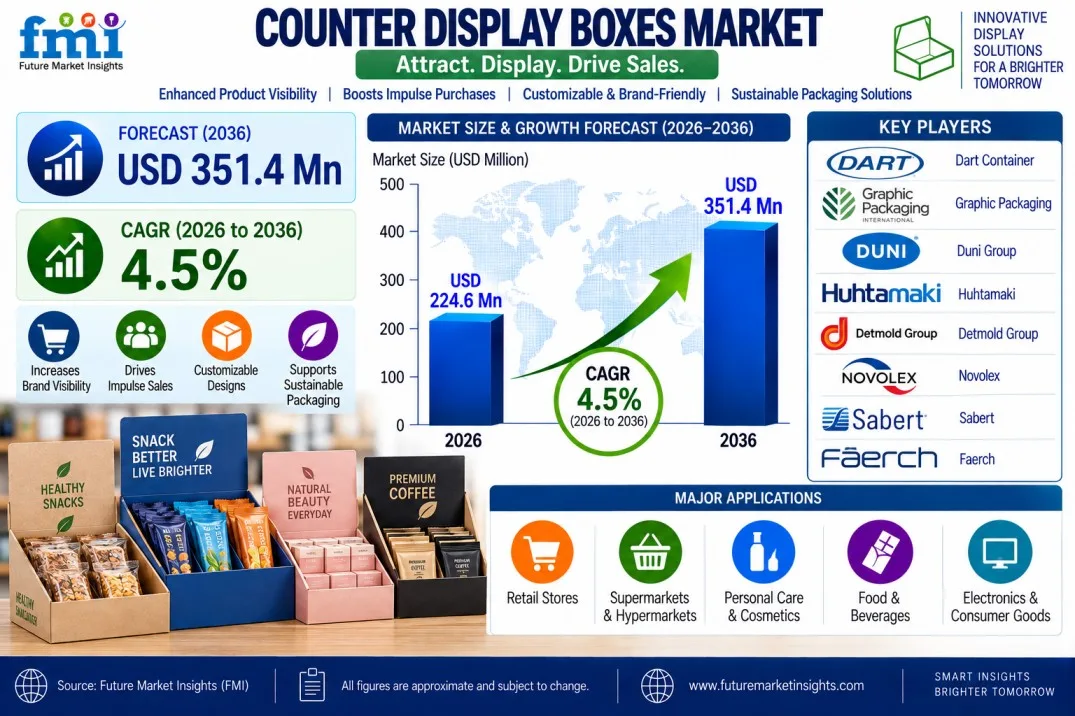
Counter Display Boxes Market Size to Reach USD 351.4 Mn by 2036, Saudi Arabia - 5.8%, USA - 4.9%

The global counter display boxes market is projected to increase from USD 226.3 million in 2026 to USD 351.4 million by 2036, advancing at a 4.5% CAGR, as foodservice and retail operators seek standardized packaging formats that combine countertop visibility, meal containment and practical end-of-life handling.

A major regulatory milestone arrived in February 2025, when the European Commission confirmed that the Packaging and Packaging Waste Regulation (EU) 2025/40 had entered into force. The regulation establishes a common framework for packaging sustainability across the European Union, increasing the importance of material composition, recyclability and packaging design in purchasing decisions.

For counter display boxes, the regulatory shift matters because the package is evaluated not only for food protection and presentation but also for how its material structure performs within local collection and recycling systems.

👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…

Why are counter display boxes becoming part of the wider packaging-design decision?

Counter display boxes serve high-turnover environments where food and packaged products need to move quickly from preparation or storage to the customer. Standardized dimensions help operators maintain predictable packing routines while reducing the number of packaging SKUs that need to be stocked across multiple locations.

Future Market Insights estimates that standard formats will account for 38.0% of format-type demand in 2026, while standard-meal sizes are projected to represent 41.0% of format-size demand.

The combination reflects a practical operating advantage. A standardized box can be qualified once against common menu portions, packing procedures and delivery conditions, then reproduced across multiple outlet
Photo 1
01 shares 2
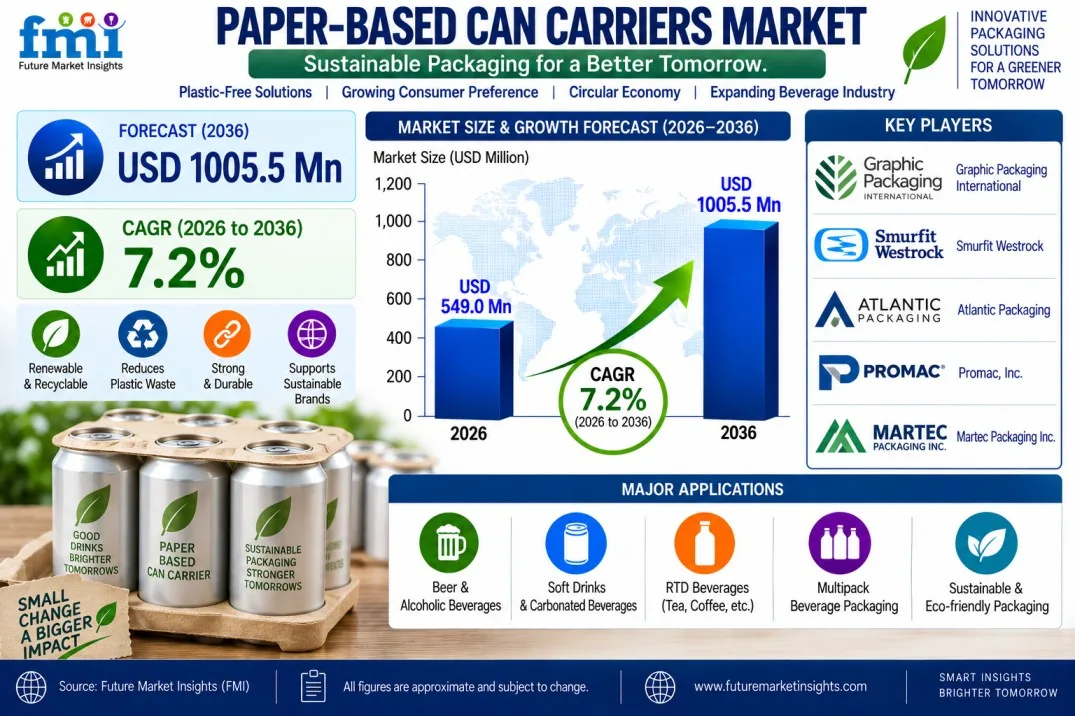
Paper-Based Can Carriers Market Growth Forecast: UK at 7.6% CAGR, Germany at 6.8% Through 2036

According to Future Market Insights, the Paper-Based Can Carriers Market is increasingly being shaped by the intersection of recyclability economics, carrier performance and line compatibility rather than material substitution alone.
👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…
Why are beverage companies shifting toward paper-based can carriers?
Paper-based carriers are gaining attention as beverage producers reassess plastic multipacks and incorporate packaging material into broader recyclability and producer-responsibility decisions.
Recycled paperboard is projected to account for 52.0% of material demand in 2026, supported by established collection and converting infrastructure. The material's commercial case depends on whether recycled grades maintain sufficient stiffness and die-cut accuracy through automated carrier application and refrigerated distribution.
Wrap carriers are expected to lead the product-type segment with 32.0% share in 2026, reflecting their ability to cover common can configurations while providing a broad printable surface.
Graphic Packaging introduced wrap-style paperboard multipacks at drinktec in September 2025, designed to operate on existing high-speed Marksman equipment. Such developments address a central conversion barrier: beverage plants are more likely to adopt alternative carriers when packaging changes do not require wholesale replacement of existing application infrastructure.
The competitive field also includes Smurfit Westrock and Atlantic Packaging, while International Paper, MM Packaging and Metsä Board participate through broader paperboard and beverage-packaging platforms.
Why does chilled performance remain a critical qualification test?
Paper carriers have to retain cans while exposed to condensation, refrigeration and handlin
Photo 1
01 shares 0
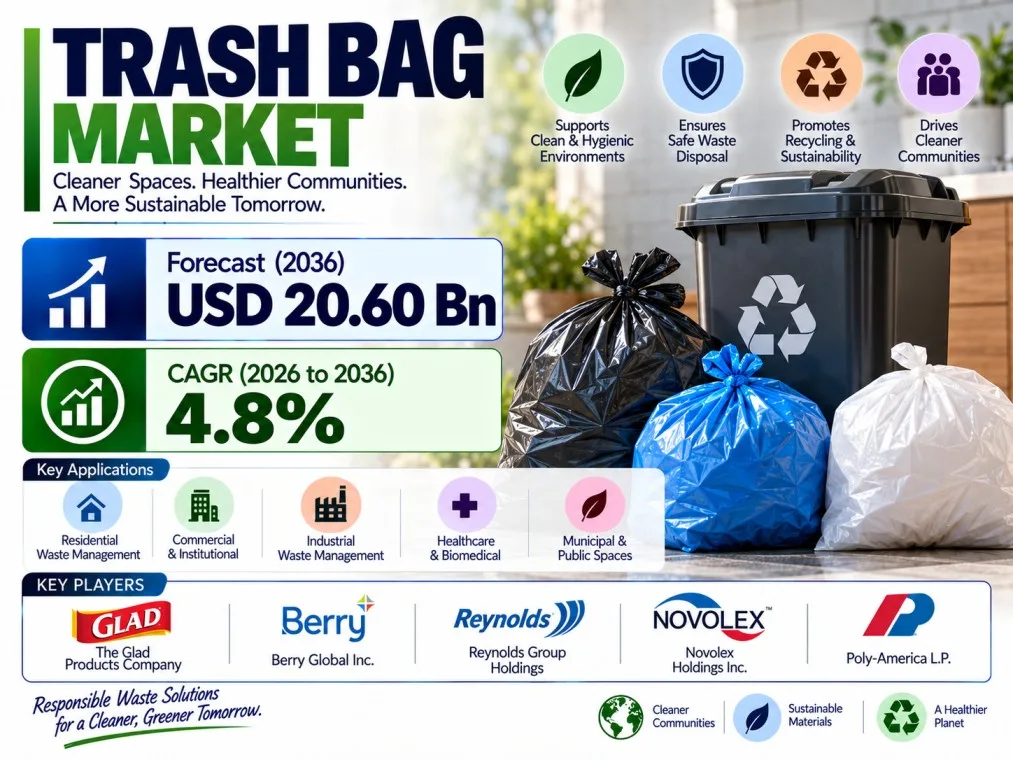
Trash Bag Market Set to Reach USD 20.60 Bn by 2036, India Records 7.2% CAGR, Germany at 5.1%

The global trash bag market is projected to reach USD 20.60 billion by 2036, up from USD 12.89 billion in 2026, registering a CAGR of 4.8% between 2026 and 2036, according to Future Market Insights (FMI).
The market was valued at USD 12.3 billion in 2025. Growth is being supported by urbanization, expanding waste management infrastructure, hygiene awareness, sustainability regulations, and increasing demand across residential, commercial, healthcare, and industrial applications.
Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…
Urbanization Creates Consistent Demand for Waste Containment
Urban population growth is increasing the volume of household, commercial, and institutional waste requiring collection and containment. As cities expand, waste management infrastructure is also creating new demand for trash bags and liners.
The relationship between urbanization and waste generation is particularly relevant in developing markets, where investments in waste collection and segregation are expanding the addressable market.
India is projected to record the fastest growth among the countries covered, with a 7.2% CAGR through 2036. Brazil follows at 6.8%, while China is projected to grow at 6.7%.
Sustainability Requirements Reshape Material Selection
Environmental regulations targeting single-use plastics and landfill reduction are influencing the specifications of trash bags.
Manufacturers are increasingly developing products using HDPE, LDPE, and biodegradable polymers, while recycled-content and compostable alternatives are gaining attention in markets where regulations require changes in material composition.
The transition also creates cost pressures. Manufacturers investing in alternative materials need to manage higher compliance and production costs while maintaining the strength,
Photo 1
01 shares 1
Decor Paper Market Forecast to Hit USD 8.8 Bn by 2036, China Growing at 6.8% CAGR, UK at 4.9%

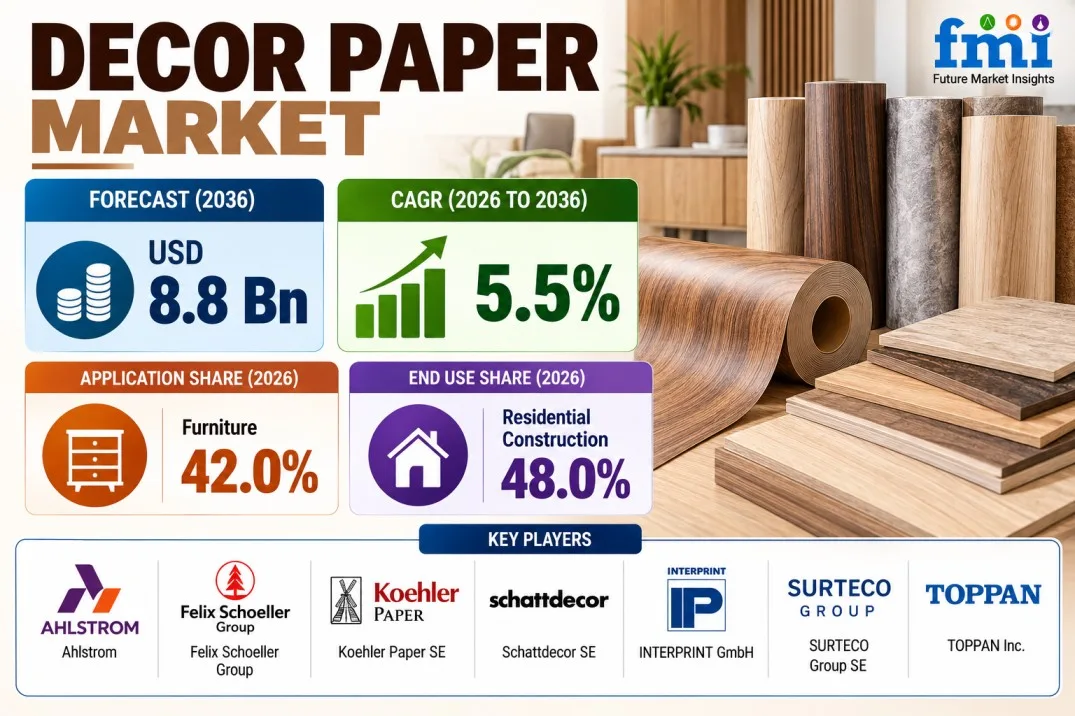
The global Decor Paper Market is projected to increase from USD 5.2 billion in 2026 to USD 8.8 billion by 2036, registering a 5.5% CAGR during the forecast period, according to Future Market Insights (FMI).

The market was valued at USD 4.9 billion in 2025. Demand is being supported by furniture manufacturing, laminate conversion, residential construction, flooring, and interior projects that require consistent printed or colored surfaces on MDF, particleboard, and other wood-based panels.

Decor paper allows furniture and interior manufacturers to create woodgrain, stone-look, and solid-color surfaces at a lower cost than natural veneer. As panel producers expand their design ranges, paper quality, print consistency, and resin performance are becoming increasingly important purchasing criteria.

👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…

Furniture Remains the Leading Application

Furniture applications are expected to account for 42.0% of market share in 2026, making them the leading application segment.

Cabinets, wardrobes, kitchen units, and other furniture products rely on decorative surfaces that remain consistent across multiple panels. This increases demand for papers capable of maintaining shade accuracy and print definition throughout large production runs.

Residential construction represents the leading end-use segment, with a projected 48.0% share in 2026.

Housing projects continue to support demand for laminated panels used in kitchens, storage systems, flooring, and interior surfaces.

Print Base Paper Leads the Paper-Type Segment

Print base paper is expected to account for 38.0% of demand in 2026.

The paper serves as the printable carrier for woodgrain, stone-look, and other decorative designs.
Photo 1
01 shares 8
Jumbo Bags Market Set to Reach USD 10.4 Bn by 2036, Brazil at 4.7% CAGR, Germany at 3.8%

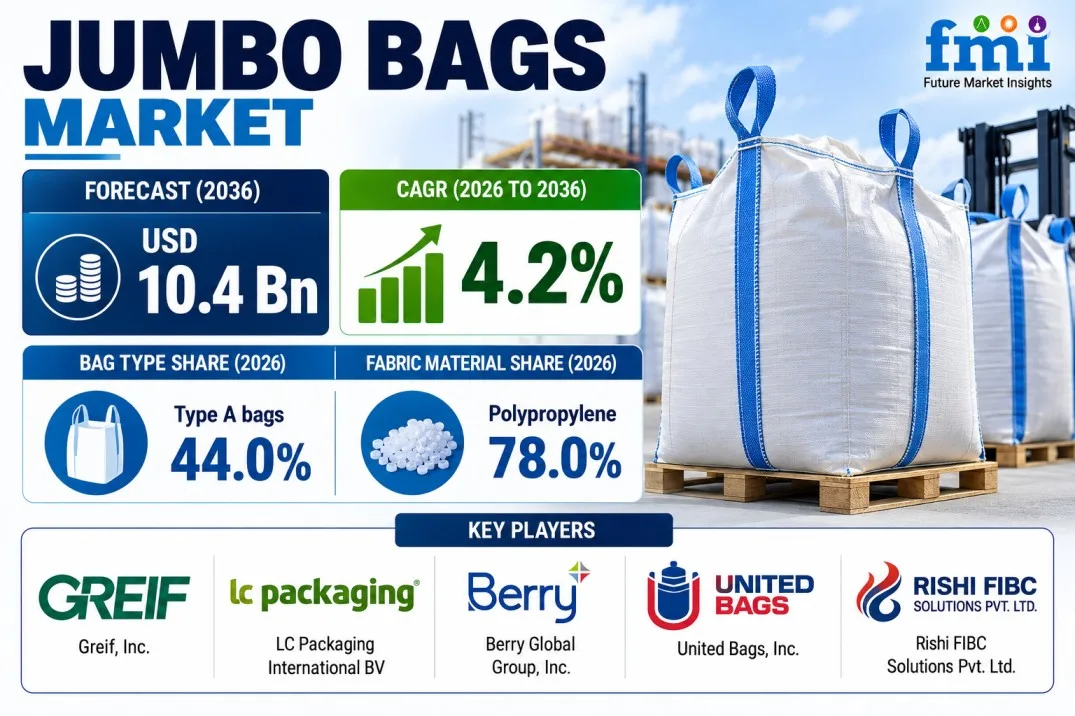
The global jumbo bags market is projected to reach USD 10.4 billion by 2036, expanding from USD 6.9 billion in 2026 at a CAGR of 4.2%, according to Future Market Insights (FMI).
The market was valued at USD 6.6 billion in 2025. Growth is being supported by increasing bulk movement of fertilizers, cement, chemicals, minerals, food ingredients, and agricultural products. Flexible intermediate bulk containers (FIBCs) help industrial users reduce manual handling while supporting stackable storage and efficient transport.

👉 Access the Complete Report in PDF Format: https://www.futuremarketinsights.com/reports/brochure/rep…
Bulk Handling Efficiency Supports Market Demand
Jumbo bags are increasingly being evaluated as part of industrial handling systems rather than simply as containers.
Fertilizer producers, chemical manufacturers, cement companies, food processors, miners, and exporters use FIBCs to move large quantities of dry materials while reducing empty-pack weight and manual handling requirements.

The 1,000 kg to 1,500 kg capacity range is expected to account for 46.0% of demand in 2026, reflecting its suitability for fertilizers, cement, resins, and other dry bulk materials.

Direct supply is also gaining importance. Large industrial accounts increasingly prefer fixed specifications and predictable replenishment schedules, with direct supply expected to reach 58.0% by 2036.

Polypropylene Remains the Dominant Material
Polypropylene is projected to maintain its position as the primary fabric material, with a 78.0% share by 2036.

Its strength-to-weight characteristics make woven polypropylene suitable for high-volume industrial packaging where customers need durable bags without adding unnecessary freight weight.

Polyethylene is used more frequently in liners and specialty structures where moisture control is particularly important.
For suppliers, fabric consistency.
Photo 1
01 shares 2
Recyclable Frozen Food Packaging Market to Cross USD 3.2 Bn by 2036, Brazil Growing at 7.4% CAGR

According to the latest analysis from Future Market Insights, the Recyclable Frozen Food Packaging Market is moving toward a more performance-led qualification process in which material selection, barrier technology and local recycling infrastructure are evaluated together.

👉 Get Detailed Market Forecasts, Competitive Benchmarking, and Pricing Trends: https://www.futuremarketinsights.com/reports/sample/rep-g…

Why are frozen-food processors reassessing recyclable packaging structures?

Recyclability is increasingly becoming part of the package specification rather than a secondary sustainability consideration. Processors must balance regulatory requirements with the physical demands of frozen-food distribution, where seals, coatings and board strength can be exposed to low temperatures and condensation.

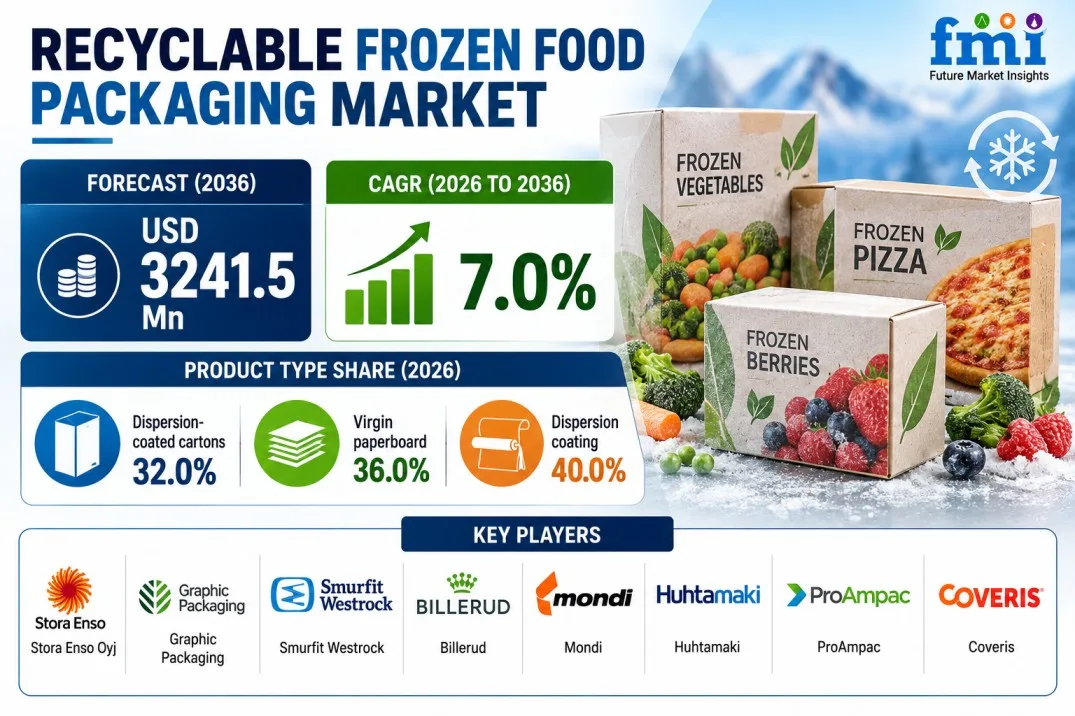
Dispersion-coated cartons are estimated to account for 32.0% of the product-type segment in 2026, making them the leading format in the assessment. Their thin barrier layers can provide moisture and grease protection while retaining a predominantly fiber-based structure.

Virgin paperboard is expected to represent 36.0% of material demand in 2026, supported by consistent fiber strength and predictable converting performance. Meanwhile, dispersion coating is projected to lead barrier technologies with a 40.0% share, reflecting demand for targeted protection that can preserve a fiber-led recovery pathway.

Stora Enso's introduction of Performa Nova for frozen and chilled food applications in April 2025 illustrates how board producers are adapting fiber-based platforms for cold-chain packaging. Billerud's CrownBoard Light, introduced in September 2025 for cold and moist environments, similarly demonstrates the emphasis on fresh-fiber board performance in demanding food applications.
Photo 1
01 shares 25